


The major indexes are struggling, but one stock caught my attention for doing the opposite.
On Tuesday, November 17, Snap Inc. SNAP 0.00%↑ surged 8.06% to close at $5.50, while the SPY, the DIA, the QQQ, and the SPDR Communication Services XLC 0.00%↑ sector finished lower.
That kind of relative strength is hard to ignore, especially when it comes with an early technical buy signal, but there’s more to this story than one strong trading day.
SNAP is making progress in profitability, subscription revenue, and cash generation and with Morningstar’s reported fair-value estimate of $7 per share, there’s a potential valuation opportunity worth examining.
Can SNAP’s improving business performance translate into a sustained stock-price recovery?
That’s what I’m digging into for this week’s Top Pick. 👑
Here’s the setup →
NIM Top Pick of the Week 👑
Ticker: SNAP 0.00%↑
Company: Snap Inc.
Sector: Communication Services XLC 0.00%↑
Industry: Internet
Valuation: Morningstar currently rates SNAP four stars with a $7 fair-value estimate.
Dividend: Nope.
Potential swing-trade target: previous high of $6.50
👑 WANT MORE TRADE IDEAS LIKE THIS?
Upgrade to an annual Nurse in the Market subscription.
Paid subscribers get my Sunday Market Playbook, Wednesday Top Pick of the Week, and the research and trade ideas I’m watching along the way.
Come join us. 👑
The Business Behind the Price Movement
SNAP is best known for Snapchat, a platform with 977 million monthly active users as of the third quarter of 2026.
That’s a massive audience, but audience size alone doesn’t make a profitable business.
What matters is whether SNAP can generate more revenue from those users while controlling costs and its latest quarterly results show some encouraging progress.
Revenue Growth | More Money From Its Audience
SNAP reported $1.72 billion in Q3 2026 revenue, up 14% year over year.
Advertising revenue grew approximately 4%, while average revenue per daily active user increased from $3.16 to $3.48.
That tells me SNAP is finding ways to generate more revenue from its user base, even as competition for advertising dollars remains intense.
Snapchat+ | A Growing Revenue Stream
SNAP’s fastest-growing revenue category isn’t advertising.
Non-advertising revenue jumped 84% year over year, led by Snapchat+, Memories Storage, and Lens+. The company now reports more than 30 million paid subscribers across its subscription offerings.
That’s an important development.
Advertising still accounts for roughly 80% of quarterly revenue, but paid products are giving SNAP another way to make money from its audience.
If that growth continues, subscriptions and other direct-revenue products could gradually reduce the company’s dependence on advertising budgets.
Profitability | A $160 Million Swing
Here’s a number that deserves attention.
SNAP moved from a $104 million net loss in Q3 2025 to a $56 million net profit in Q3 2026, an improvement of approximately $160 million.
Revenue grew 14%, while total costs and expenses increased by less than 1%.
That’s operating leverage: revenue is growing much faster than expenses, allowing more of it to reach the bottom line, but there’s an important distinction.
SNAP still reported a $196 million net loss for the first nine months of 2026.
One profitable quarter is progress. Consistent profitability is what I’m looking for next.
Cash Flow | Is the Improvement Sustainable?
For me cash flow is one of the strongest parts of this investment thesis.
SNAP generated $164 million in free cash flow during Q3, up 76% year over year, while operating cash flow climbed 44% to $210 million.
Stronger cash generation gives the company more flexibility to fund operations and invest in its future, but I also want that progress to benefit shareholders.
SNAP reported approximately 1.93 billion shares outstanding including shares underlying stock-based awards, up 3.8% from a year earlier.
That’s why I’m watching dilution alongside cash flow. Growing the business is important, but so is protecting the value of each share.
Valuation & Risks | Is SNAP Worth the Price?
Morningstar’s reported $7 fair-value estimate puts SNAP’s potential upside at approximately 27.3% from its November 17 closing price of $5.50.
Put another way, the stock trades about 21.4% below that estimate.
The valuation interests me because SNAP is showing measurable improvements in revenue growth, profitability, and cash flow.
However, an analyst’s fair-value estimate is an opinion about what a business may be worth; not a promise that its stock will reach that price and SNAP has real risks.
Advertising still generates most of its revenue, leaving the company exposed to competition from Meta, TikTok, and YouTube, as well as changes in advertising spending.
SNAP also needs to prove it can sustain profitability while managing expenses, stock-based compensation, and dilution.
The discount gets my attention: the business performance has to justify it.
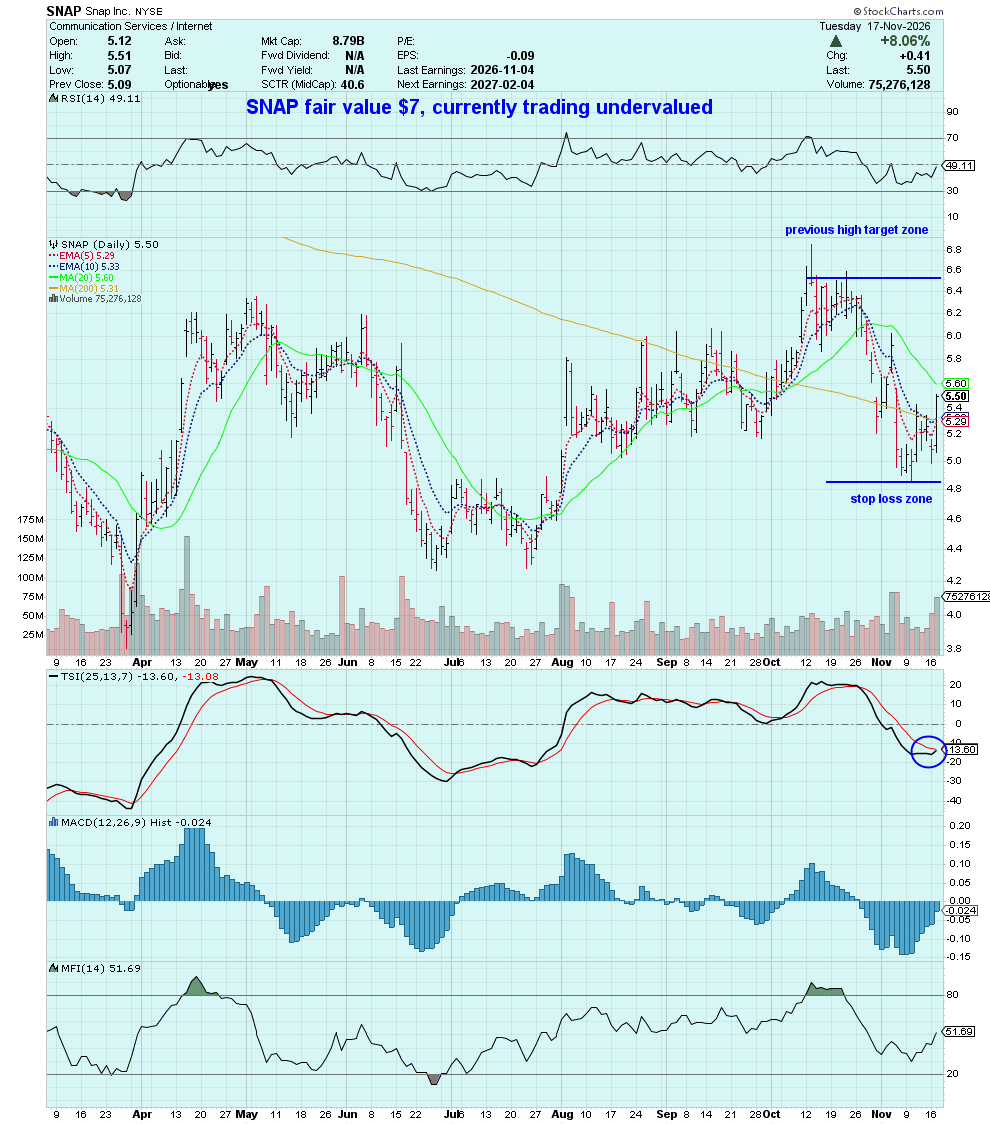
SNAP chart annotation →
Technical Setup & Trade Plan | What Does the Chart Say?
SNAP’s November 17 rally produced an early technical buy signal, with the stock closing at $5.50, above its 5-day exponential moving average (EMA) at $5.29.
Its Relative Strength Index (RSI) reading reached 49.11, suggesting momentum is recovering without yet reaching overbought territory.
I like seeing a stock show relative strength when the broader market is weak, but here’s the catch: SNAP is still below two important moving averages.
The 20-day simple moving average (SMA) at $5.60 is the first resistance level I’m watching. Above that sits the 200-day SMA at $5.81.
Those are the levels buyers need to overcome before I’d consider the broader technical recovery more convincing.
On the downside, I’m watching the $5.29–$5.33 area, where the short-term moving averages could provide initial support. If that area fails, the recent $4.80–$4.90 low zone becomes important.
The Reward-to-Risk Reality Check
Here’s why I’m not interested in chasing an 8% rally.
From SNAP’s $5.50 close:
$5.60 resistance: approximately 1.8% higher.
$5.81 resistance: approximately 5.6% higher.
$4.90 downside reference: approximately 10.9% lower.
Those levels aren’t a complete trade setup by themselves.
They’re reference points that show how much nearby resistance stands between SNAP and a stronger breakout and right now, the potential downside to recent lows is larger than the upside to either nearby resistance level.
That doesn’t mean SNAP can’t move higher. It means I want a better setup before taking on that risk.
👑 LIKE HOW WE BREAK DOWN A TRADE?
Market. Sector. Stock. Setup. Research.
That’s what we do inside Nurse in the Market every week.
Get exclusive acccess to the Sunday Market Playbook, Wednesday Top Pick of the Week, and the trade ideas and research I’m watching in between.
Come trade the Big Picture with us. 👑
My Trade Plan
I’m watching for SNAP to hold its short-term moving averages and make a convincing move above $5.60, followed by $5.81.
A sustained breakout, or a successful retest of reclaimed resistance as support, would give me more confidence than chasing a single strong session.
If SNAP loses the $5.29–$5.33 area, I’ll reassess the setup rather than assume the early buy signal will hold.
Morningstar’s $7 fair-value estimate gives me a longer-term valuation reference, but the chart has to earn its way there.
The buy signal earned SNAP my attention. What happens at resistance will determine my next move.

The Bottom Line: SNAP Has Something to Prove
SNAP is showing signs of a business turnaround, with improving profitability, growing non-advertising revenue, and stronger cash flow.
Its relative strength during a weak market makes the chart worth watching, while Morningstar’s $7 fair value estimate points to a possible valuation opportunity, but the next test isn’t whether SNAP can deliver another exciting green day.
It’s whether buyers can push through $5.60 and $5.81 and hold those gains.
Until then, I’m keeping SNAP on my watchlist rather than chasing a rally into resistance.
Following a systematic approach, reading market structure, and staying disciplined compounds over time.
Let me know what you’re watching and thank you so much for reading! 🙌
-Nurse Jess 🤝
Know the Big Picture. Focus on the Edge. 👑
Recent Top Picks of the Week
Top Pick of the Week: TSM is Back — Why I Keep Trading Stocks I Know

We took profits in TSM in early October.
Top Pick of the Week: Strong Growth, But Is It a Buy?

Amazon caught my attention in Sunday’s Market Playbook when it was trading around $242, roughly 14% below Morningstar’s $280 fair-value estimate.
Top Pick of the Week: A Rare Bright Spot in a Weak Market

Sometimes the best trade is the one you don’t take.
📌 Bookmark this post. Track these setups through the week and see how they play out. This is how you develop an edge—by studying real-time trade ideas and learning what works.
Financial Disclaimer: This is not financial advice. All trades carry risk. Biotech stocks are highly volatile and speculative. Always do your own due diligence and consult with a financial advisor before making investment decisions.
Scan the QR code below to subscribe to Nurse in the Market →
👑 SNAP is showing signs of a turnaround, but I'm watching for confirmation before chasing the rally.
The improving fundamentals caught my interest. The relative strength got my attention. Now I'm watching whether SNAP can break above $5.60 and $5.81 and hold those levels.
📈 What do you think? Is SNAP an overlooked turnaround opportunity, or does the risk still outweigh the potential reward?
I'd love to hear what you're seeing on the chart or in the business. 👇