


Sometimes the best trade is the one you don’t take.
I planned to feature Amazon AMZN 0.00%↑ as Wednesday’s Top Pick, but the broader market wasn’t giving me the confirmation I wanted. So I waited.
By Friday, AMZN’s setup had weakened, the major indexes were selling off, and the Nasdaq-100 QQQ 0.00%↑ had fallen more than 3% for the day.
However, one stock caught my attention.
Verizon VZ 0.00%↑ .
While the broader market struggled, VZ gained roughly 2.5% on Friday and reclaimed its short-term moving averages.
That’s the kind of relative strength I pay attention to and there’s more to the story than Friday’s price action.
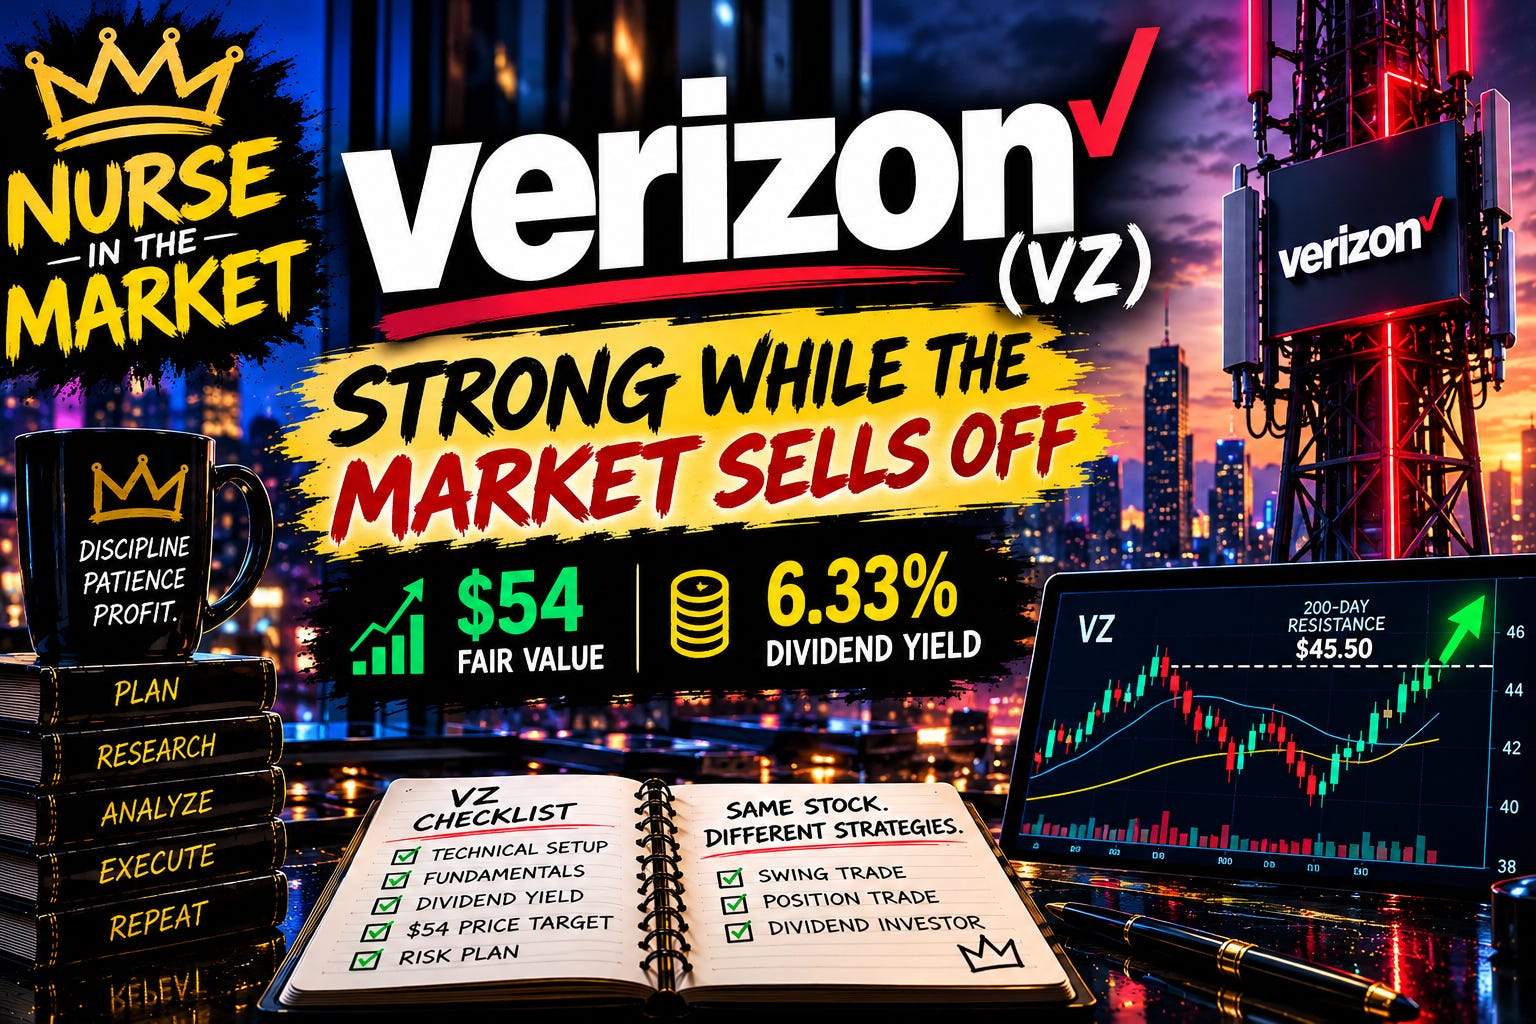
According to Morningstar, VZ is trading approximately 17% below its $54 fair-value estimate, while offering a 6.33% forward dividend yield.
That creates an interesting opportunity for traders looking for price appreciation and investors seeking long-term dividend income, but there’s a catch.
VZ still has technical resistance overhead, and an attractive valuation doesn’t automatically make a stock a bargain.
So let’s look at what the charts and fundamentals are telling us—and what could go wrong.
Here’s the setup →
NIM Top Pick of the Week 👑
Ticker: VZ 0.00%↑
Company: Verizon Communications
Sector: Communication Services XLC 0.00%↑
Industry: Fixed Telecommunications
Valuation: Morningstar currently rates VZ four stars with a $54 fair-value estimate.
Dividend: Yes. VZ pays a quarterly dividend with a 6.33% yield.
Potential swing-trade target: previous high of $50
👑 WANT MORE TRADE IDEAS LIKE THIS?
For October, you can get 22% off an annual Nurse in the Market subscription.
Paid subscribers get my Sunday Market Playbook, Wednesday Top Pick of the Week, and the research and trade ideas I’m watching along the way.
22% off. October only. Come join us. 👑
VZ chart annotation →
I. The Technical Setup: Buyers are Returning, but Resistance is Waiting
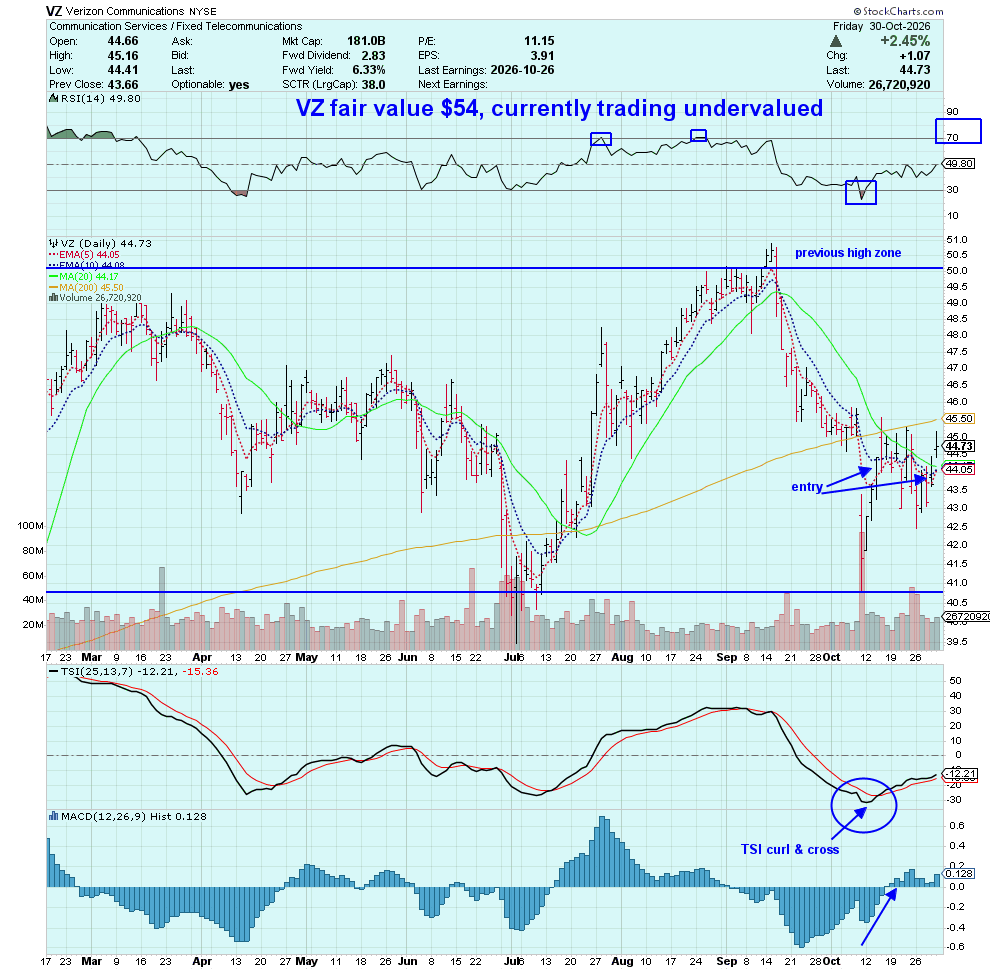
While the major indexes struggled Friday, VZ gained approximately 2.5%, closing at $44.73.
That stands out, particularly with the Communication Services sector XLC 0.00%↑ under pressure.
More importantly, VZ has reclaimed its short-term moving averages.
Friday’s close was above its 5-day EMA, 10-day EMA, and 20-day SMA.
Momentum is improving, too. The RSI recovered to 49.80, approaching the neutral 50 level. The MACD histogram turned positive, while the TSI continued recovering despite remaining below zero.
These are encouraging signs that selling pressure may be easing, but buyers have another test ahead.
🎯 The 200-Day SMA: Resistance, Not Our Target
VZ’s 200-day SMA sits near $45.50, less than 2% above Friday’s close.
That’s the first major resistance level I’m watching.
A sustained move above the 200-day SMA would strengthen the recovery setup. A rejection could lead to another pullback, but $45.50 isn’t my price target.
I’m interested in VZ’s potential recovery toward Morningstar’s $54 fair-value estimate.
For now, I want to see price hold its recently reclaimed short-term moving averages while momentum continues improving.
Friday’s strength was encouraging. The next test is whether buyers can follow through.
In other words:
→ this is an amazing buy & hold opportunity to pick up shares of VZ, an undervalued dividend stock to hold for the long-term, if not forever.
→ we can also position trade VZ back to true value and beyond and make massive gains.
→ we can take a simple swing trade to the previous high zone around $50.
→ if you’re an experienced, astute trader, you can write option contracts on VZ and do what you do and make exponential gains.
II. The Fundamentals: Strong Cash Flow, A Big Dividend, and An Emerging AI Opportunity
VZ isn’t exactly the first company that comes to mind when investors talk about AI, but its latest earnings report gave me a reason to look closer.
The company is showing signs of operational improvement while exploring additional revenue opportunities through its network infrastructure and at its current valuation, that’s worth investigating.
Earnings: Progress, With Room to Improve
VZ reported 406,000 postpaid phone net additions in the third quarter, its strongest third-quarter performance in five years.
Revenue increased 1.5% to $34.3 billion, while adjusted earnings per share rose 8.3% to $1.31.
The company also raised its full-year guidance for the third consecutive quarter.
Those are encouraging developments, but here’s the distinction that matters: Reported revenue growth benefited from the Frontier acquisition.
Morningstar estimates revenue would have declined approximately 3% without Frontier, while core wireless and broadband revenue grew only modestly.
So while profitability and customer additions are improving, VZ still needs to demonstrate stronger underlying growth.
The recovery story is developing. It isn’t finished.
An Unexpected AI Infrastructure Opportunity
Here’s something I didn’t expect to find in VZ’s investment story.
The company announced an agreement valued at more than $2 billion with Amazon Web Services (AWS) involving network infrastructure for AI workloads.
As AI adoption expands, businesses need high-capacity connections between data centers and computing facilities.
VZ’s network could help meet that demand.
It’s a potential way for Verizon to benefit from AI infrastructure spending without developing chips or AI models, but I’m keeping expectations realistic.
The reported agreement value doesn’t tell us how much revenue VZ will recognize in any given period, how profitable the work will be, or how quickly it will contribute to earnings.
For now, I see AI infrastructure as a possible additional growth opportunity—not the foundation of my investment thesis.
The Dividend: Follow the Cash Flow
For long-term investors, VZ’s cash generation may be the more compelling story.
The company reported $7.8 billion in third-quarter free cash flow, up 12.1% year over year.
Through the first nine months of 2026, Verizon generated approximately $18 billion in free cash flow, compared with $8.8 billion paid in dividends.
That’s encouraging dividend coverage.
At Friday’s closing price, Morningstar reported a 6.33% forward dividend yield, but there’s another number investors shouldn’t overlook.
VZ reported $123.7 billion in net unsecured debt at quarter-end.
That makes continued cash generation and debt management especially important.
A substantial dividend can reward patient shareholders, but I want to see the company maintain enough financial flexibility to invest in its network, manage its debt, and support future payments.
The yield gets my attention. Cash flow determines whether I want to keep holding.
Valuation: Is $54 Reasonable?
Morningstar assigns VZ a $54 fair-value estimate and a four-star rating.
At Friday’s $44.73 close, that represents approximately 20.7% potential price appreciation, excluding dividends.
That’s attractive, but Morningstar also assigns the stock a high uncertainty rating, reflecting the competitive and financial challenges facing the business.
T-Mobile TMUS 0.00%↑ and AT&T T 0.00%↑ remain formidable competitors. Organic growth is modest, and VZ carries substantial debt.
The opportunity is that VZ may be undervalued. The risk is that its business takes longer than expected to justify a higher share price.
That’s the balance I’m weighing.
III. The Trade Plan: Three Strategies. Different Reasons to Own VZ.
VZ offers potential price appreciation toward Morningstar’s $54 fair-value estimate, along with an income opportunity for longer-term shareholders, but the strategy matters.
For Swing Traders
I’m watching VZ for a potential move toward $54, approximately 20.7% above Friday’s close.
Under my trading framework, a close above the 5-day EMA while price remains below the 200-day SMA provides an initial entry signal.
Friday’s close met that condition.
Still, the broader market remains weak, and VZ faces resistance near its 200-day SMA at $45.50.
I’ll be watching whether price can hold its reclaimed short-term moving averages and continue building momentum.
A sustained move back below those averages would be an early warning that the recovery is losing strength.
My upside objective is $54, but I won’t assume the stock gets there quickly—or at all.
For Position Traders
Position traders may be willing to give VZ more time to work toward estimated fair value.
That means allowing for normal price fluctuations while monitoring the business and the technical trend.
I’d reassess the thesis if earnings weaken, cash generation deteriorates, or the valuation outlook changes materially.
The $54 estimate is a reference point, not a deadline or guaranteed exit price.
For Long-Term Dividend Investors
For investors focused on income, VZ’s 6.33% forward dividend yield offers a different reason to consider the stock.
The longer-term opportunity is collecting dividends while potentially benefiting from share-price appreciation, but dividend investors need to pay particular attention to free cash flow, dividend coverage, debt reduction, and competitive performance.
Those factors matter more to a long-term income strategy than a short-term moving-average crossover and dividends can be reduced or suspended.
👑 LIKE HOW WE BREAK DOWN A TRADE?
Market. Sector. Stock. Setup. Research.
That’s what we do inside Nurse in the Market every week.
For October, an annual subscription is 22% off, giving you access to the Sunday Market Playbook, Wednesday Top Pick of the Week, and the trade ideas and research I’m watching in between.
Come trade the Big Picture with us. 👑
IV. My Approach
I’m interested in VZ, but I’m not giving the broader market a free pass.
The stock is showing relative strength, and Friday’s close met my initial technical entry condition.
For a swing or position trade, I’d monitor the recent recovery area and treat a sustained loss of short-term support as a reason to reassess.
The precise stop belongs below a chart-defined support level and should be set before entry, based on the position size and risk I’m willing to accept.
For long-term ownership, the decision rests more heavily on VZ’s financial performance and dividend sustainability.
Same stock. Different strategies. Know why you’re buying before deciding when to sell.
V. The Bottom Line: Sometimes Waiting Reveals a Better Opportunity
I didn’t publish a Top Pick on Wednesday because I didn’t like what the broader market was telling me.
By Friday, the indexes had weakened further, but Verizon VZ 0.00%↑ was moving in the opposite direction.
That’s why VZ earned my attention.
I’m interested in its potential recovery toward Morningstar’s $54 fair-value estimate, with a separate case for long-term dividend ownership, but I’m watching how the stock handles resistance and whether buyers continue showing up.
If the setup weakens, I’ll reassess.
I don’t need the entire market to cooperate. I need the stock I’m trading to give me a reason to act and right now, VZ is giving me one.
Following a systematic approach, reading market structure, and staying disciplined compounds over time.
Let me know what you’re watching and thank you so much for reading! 🙌
-Nurse Jess 🤝
Know the Big Picture. Focus on the Edge. 👑
Previous Top Picks of the Week


Top Pick of the Week: Google Again? Yep. And That’s Exactly the Point.

Alphabet Inc. was our Top Pick of the Week on June 17th and here we are in October and GOOGL is back.
📌 Bookmark this post. Track these setups through the week and see how they play out. This is how you develop an edge—by studying real-time trade ideas and learning what works.
Financial Disclaimer: This is not financial advice. All trades carry risk. Biotech stocks are highly volatile and speculative. Always do your own due diligence and consult with a financial advisor before making investment decisions.
Scan the QR code below to subscribe to Nurse in the Market →
👑📈 Sometimes the best trade is the one you wait for.
I passed on Amazon Wednesday because the market wasn't giving me confirmation. By Friday, VZ was showing relative strength while the major indexes sold off.
I'm watching $45.50 as resistance and $54 as a potential upside target, with that 6.33% dividend adding another angle for long-term investors.
What about you? Are you looking at VZ as a swing trade, a longer-term position, or a dividend investment? Or are you staying on the sidelines until the market settles down?
👇 I'd love to hear how you're approaching it.
Know the Big Picture. Focus on the Edge. 👑